Data intelligence for high-level investment decisions
Deploy your AI-optimized portfolio in less than 60 seconds. Real-time predictive analytics for remote professionals looking for scalable, location-independent revenue.
Start Analysis Now
Deploy your AI-optimized portfolio in less than 60 seconds. Real-time predictive analytics for remote professionals looking for scalable, location-independent revenue.
Start Analysis NowAn independent investor who manually reviews quarterly reports, macro indicators and historical series usually takes hours to reach an operational conclusion. In volatile markets, that time becomes an opportunity cost.
Templado Plazanza replaces manual review with a continuous processing model, capable of comparing thousands of variables simultaneously and returning a structured recommendation before the decision window closes.
The system does not make decisions without traceability. Each recommendation can be traced back to the data and model that generated it.
Market data, historical series and macroeconomic indicators are integrated into a single structured flow, without manual loading intervention.
Risk neural networks evaluate variance, correlation and sensitivity of each asset against different market scenarios.
The engine delivers a prioritized portfolio assignment, ready for review and execution, without additional manual steps.
Each engine component was designed to reduce analysis work, not replace user judgment.
The engine updates market positions and variables continuously, avoiding decisions based on outdated information.
The expected variance of each asset is calculated through historical backtesting, allowing scenarios to be compared before allocating capital.
When the portfolio composition deviates from the defined risk parameters, the system proposes adjustments based on evidence, not emotional reaction.
The data architecture allows you to operate on multiple markets and asset classes from the same panel, without depending on the user's physical location.
Templado Plazanza was built with professionals who work from any location in mind and who need objective criteria to allocate capital without dedicating full days to financial analysis.
The team prioritizes algorithmic efficiency over the promise of performance: every model update is documented and available for user review.
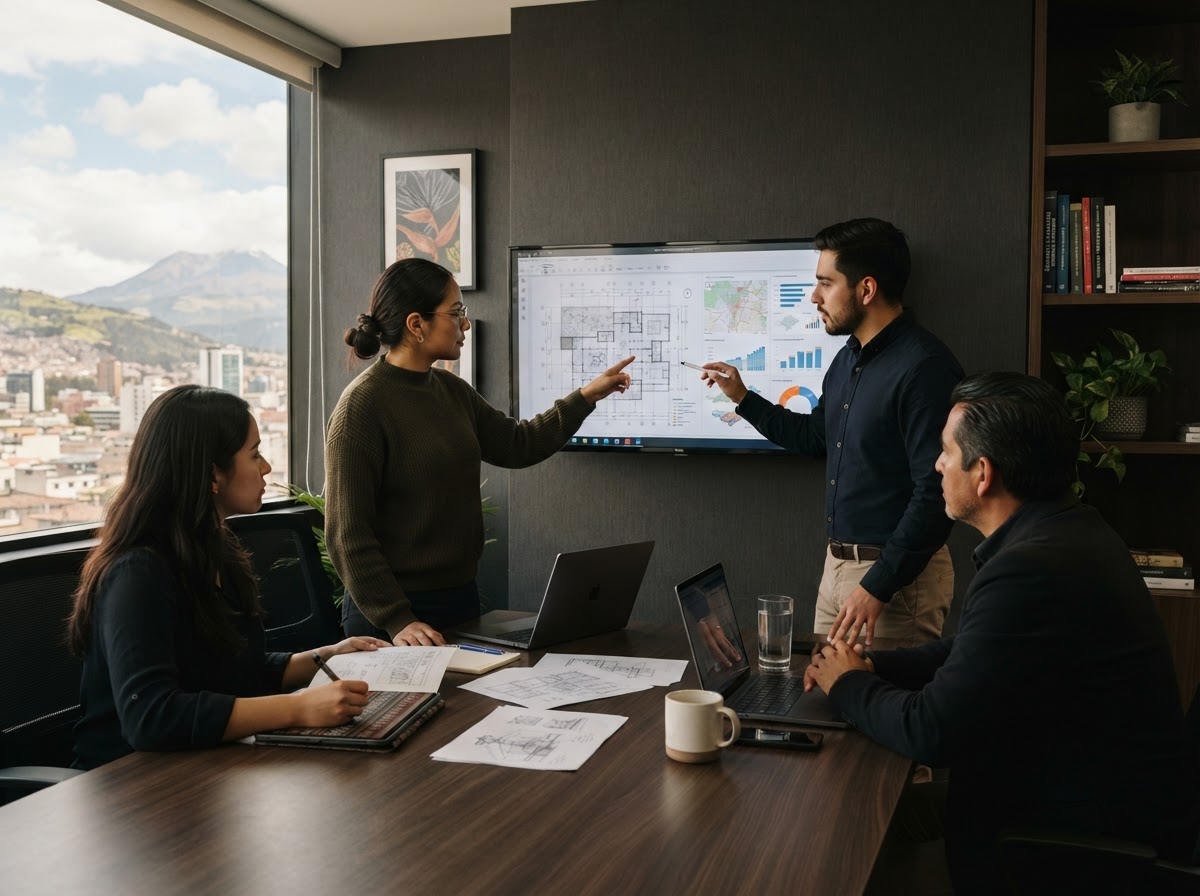
The same optimization engine adapts to different financial objectives, without requiring additional technical configuration.
A remote professional in Ecuador configures his portfolio once and receives rebalancing alerts only when the model detects a relevant risk deviation.
Those who trade most frequently use risk modeling to validate opportunities before executing, reducing decisions based on isolated intuition.
Long-term-oriented profiles use historical backtesting to adjust risk exposure as their income changes, without depending on an in-person advisor.
These answers summarize how the data is processed and where the recommendations generated by the system come from.
Portfolio connection and configuration data is stored in encrypted form and is only used for the calculation of recommendations within the user's account. They are not shared with third parties for commercial purposes.
The model combines historical series with variance and correlation indicators between assets. Each recommendation includes the most important factors in the calculation, so that the user can review the logic before acting.
The optimization engine works with relative proportions and weights, not fixed amounts. This allows the allocation logic to be applied consistently regardless of available capital.
Initial setup takes less than 60 seconds and requires no prior programming or financial modeling knowledge.